Iberian Belt West Project Pre-Feasibility Study Highlights
- Initial Probable Mineral Reserve of 23.4 million tonnes at 2.30% zinc, 1.13% lead, 0.45% copper, 53 g/t silver, 1.07 g/t gold
- Updated Mineral Resource Estimate reflects a 37% increase in Indicated tonnage and a 46% increase in Inferred tonnage compared to the 2025 MRE
- After-tax NPV (8%) of US$776 million and IRR of 23.51% in real terms
- After-tax payback period of 1.9 years from the start of production
- Initial capital cost of US$567 million including contingency
- Life-of-mine of 21 years with an average annual run of mine production of 1.2 million tonnes per year
- Conventional flowsheet producing four saleable concentrates of precious metals-bearing pyrite, zinc, lead and copper
- At achieved capacity, IBW is expected to produce average annual concentrate production of 43,489 tonnes of zinc concentrate, 26,120 tonnes of lead concentrate, 10,633 tonnes of copper concentrate, and 694,620 tonnes of pyrite concentrate on a dry metric tonne basis
- Precious metals-bearing (Au, Ag) pyrite concentrate with a high sulphur grade, the value of which is significantly influenced by contained gold and silver and the sulphur content
- Opportunities to further optimize IBW identified in the PFS, including development and sequence optimization, potential resource and reserve additions, exploration of satellite or new deposits, and metallurgical optimization, each of which requires further study
- The PFS was prepared by SLR Consulting, including qualified persons with experience in the Iberian Pyrite Belt
Toronto, Ontario--(Newsfile Corp. - October 29, 2026) - Emerita Resources Corp. (TSXV: EMO) (OTCQX: EMOTF) (FSE: LLJA) (the "Company" or "Emerita") is pleased to announce the positive results of a Pre-Feasibility Study ("PFS") prepared in accordance with National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101") for its 100%-owned Iberian Belt West project ("IBW") located in the Iberian Pyrite Belt, Huelva Province in southwestern Spain. Unless otherwise noted, all dollar amounts ($) are expressed in US dollars (US$).
Joaquin Merino, Emerita's President and CEO, comments "The completion of IBW's PFS is the culmination of 2 years of studies involving various technical disciplines including mining and process engineering, metallurgy, geology, environmental science and commodity marketing. The PFS demonstrates the technical and economic viability of developing IBW into a high-grade polymetallic underground mine in the Iberian Pyrite Belt at a pre-feasibility level of study and identifies opportunities to further optimize IBW. The Company remains committed to the sustainable social and economic development of the region where it operates for the benefit of all stakeholders and local communities."
Emerita's Executive Chairman, Joseph Belan, adds, "Before announcing the PFS results, Emerita implemented a thorough review process, which included a rigorous technical and financial review of the underlying assumptions, methodology and conclusions. A technical committee, consisting of two (2) independent members of the Board, was also established to provide additional oversight of the PFS results and optimization recommendations."
IBW is royalty-free, 100% owned, and hosts three high-grade polymetallic deposits (La Romanera, El Cura, and La Infanta), all of which remain open along strike and at depth. IBW is situated in the Iberian Pyrite Belt, widely regarded as one of the most significant volcanogenic massive sulphide-producing geological belts in the world. Emerita currently holds 15,023 hectares of land grants in the Iberian Pyrite Belt, including IBW which comprises 1,546 hectares. Emerita's additional land holdings in the Iberian Pyrite Belt provide further exploration opportunities in the region.
IBW benefits from existing regional infrastructure, including proximity to the Port of Huelva, established transportation routes and renewable energy infrastructure. Emerita believes these factors may help reduce permitting and development timelines, as well as capital requirements; however, permitting, development timelines and capital requirements remain subject to material risks, including environmental approvals, engineering, water management, community engagement, regulatory review, financing, procurement, construction execution and commodity-market conditions.
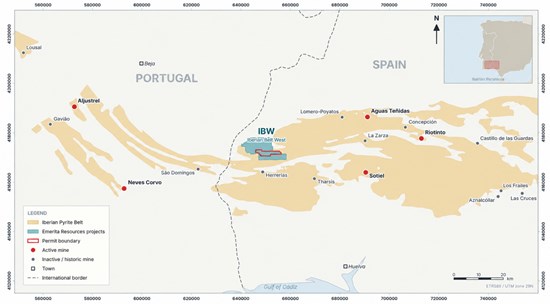
Source: Emerita Resources
Figure 1. IBW Location in the Iberian Pyrite Belt
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_5cfbd225742a7b3b_001full.jpg
2026 Pre-Feasibility Study Results
The PFS supports an underground mining operation processing material from the La Romanera, El Cura and La Infanta deposits through a conventional flotation plant producing four saleable concentrates of precious metals (gold, silver) bearing pyrite, zinc, lead and copper. The PFS indicates positive project economics with significant leverage to sulphur, silver, gold, zinc, copper, and lead prices, a 21-year life-of-mine, and potential opportunities for further optimization. Table 1 shows the IBW PFS's economic and operational summary.
Table 1. Economic and Operational Summary of IBW Pre-Feasibility Study
| Table 1. Economic and Operational Summary of IBW Pre-Feasibility Study | Units | PFS (Base Case) |
| Long-Term Metal Price Assumptions |
| Copper Price | US$/t | 11,470 |
| US$/lb | 5.20 |
| Lead Price | US$/t | 2,050 |
| US$/lb | 0.93 |
| Zinc Price | US$/t | 2,980 |
| US$/lb | 1.35 |
| Gold Price | US$/oz | 3,750 |
| Silver Price | US$/oz | 52 |
| Pyrite Concentrate Price | US$/t concentrate | 274 |
| Life-of-Mine Capital Cost Summary |
| Total Initial Capital Costs | US$ million | 566.7 |
| Sustaining Capital | US$ million | 279.5 |
| Closure Costs (Post-mine activities) | US$ million | 12.0 |
| Total Project Capital | US$ million | 858.2 |
| Life-of-Mine Unit Operating Costs (Year 1 to Year 21) |
| Mining Operating Costs | US$/t ore processed | 37.61 |
| Processing Costs | US$/t ore processed | 30.20 |
| Contact Water Treatment | US$/t ore processed | 3.52 |
| Capital Recovery Charge for Water Treatment Plant | US$/t ore processed | 6.06 |
| Mine waste / ATEM | US$/t ore processed | 0.15 |
| Tailings / IPS | US$/t ore processed | 0.53 |
| Paste Backfill | US$/t ore processed | 5.24 |
| G&A | US$/t ore processed | 2.97 |
| Progressive Rehabilitation | US$/t ore processed | 0.22 |
| Total Operating Costs | US$/t ore processed | 86.49 |
| Total On-Site Operating Costs, LOM | US$ million | 2,028 |
| Total Off-Site Costs, LOM | US$ million | 886 |
| Production Summary |
| Commencement of production |
| Year 1, following mine development in Years -5 to -1 |
| Probable Mineral Reserve (Total ore feed to flotation) | Mt | 23.4 |
| Average Grade, Zn | % | 2.30 |
| Average Grade, Pb | % | 1.13 |
| Average Grade, Cu | % | 0.45 |
| Average Grade, Ag | g/t | 53.21 |
| Average Grade, Au | g/t | 1.07 |
| Average Grade, S | % | 33.85 |
| Plant Throughput (Nominal design) | ktpa | 1,200 |
| Life-of-Mine, Ore Processed | years | 21 (Years 1 to 21) |
| Recovery of Primary Commodity to Concentrate, Zinc concentrate | % | 78.65 |
| Recovery of Primary Commodity to Concentrate, Lead concentrate | % | 52.19 |
| Recovery of Primary Commodity to Concentrate, Copper concentrate | % | 41.48 |
| Recovery of Sulphur to Pyrite Concentrate | % | 93.62 |
| Recovery of Silver to Pyrite Concentrate | % | 87.63 |
| Recovery of Gold to Pyrite Concentrate | % | 88.42 |
| Concentrate Grade |
| 50.1% Zn; 26.76% Pb; 20.43% Cu; 50.67% S |
| Concentrates Produced, LOM: zinc / lead / copper / pyrite concentrate | dmt | 845,652 / 514,778 / 213,080 / 13,573,653 |
| Average Annual Tonnage, Yr 2 to Yr 19: zinc / lead / copper / pyrite concentrate | dmt | 43,489 / 26,120 / 10,633 / 694,620 |
| Total Payable for Concentrates, LOM: zinc / lead / copper / pyrite concentrate | US$ million | 1,145 / 739 / 852 / 4,737 |
| Project NSR Contribution by Concentrate Type: pyrite / zinc / lead / copper concentrate | % | 66 / 14 / 10 / 10 |
| Summary of Base Case Economic Results |
| NPV (Real, After-tax) @ 8% | US$ million | 776 |
| IRR (Real, After-tax) | % | 23.51 |
| Payback Period from Production Commencement |
| 1 year, 11 months |
| Payback Period from Initial Investment |
| 6 years, 11 months |
| Earnings Before Interest, Taxes, Depreciation, and Amortisation (EBITDA), LOM | US$ million | 4,559 |
| Post-Tax-Free Cash Flow, LOM | US$ million | 2,664 |
| Profitability Index (PI) | x | 2.37 |
| NPV/Initial Capex Ratio | x | 1.37 |
Source: SLR
At higher exchange-traded metal prices consistent with September 2026 average spot prices for gold, silver, copper, zinc and lead (see Table 8), with the pyrite concentrate price held at the Base Case assumption, IBW's after-tax NPV (8%) increases to $1,019 million with an after-tax IRR of 27.13% and a reduced payback period after start of production of 1 year and 6 months.
While several processing routes were considered for the PFS, trade-off analysis indicated that additional metallurgical testing would be required for these routes to support a pre-feasibility level of study. As a result, the PFS adopts a conventional metallurgical flowsheet producing a saleable pyrite concentrate, with lower capital and operating cost inputs and a reduced tailings management footprint. Emerita has previously reported positive metallurgical results using alternative technologies. These and other available technologies may provide future optionality for IBW.
Unlike copper, zinc, lead, gold or silver, pyrite concentrate is not traded on a metals exchange. Pricing is negotiated under offtake or sales contracts and is typically based on the contained gold and silver (subject to payability) together with the sulphur content. The latter has value as a feedstock for sulphuric acid production, fuel in copper smelting and as a native sulphur source used in fertilizers and other industrial applications. The pricing adopted in the PFS for pyrite concentrate material is based on a market analysis that formulated long-term average pricing assumptions. These assumptions considered metallurgical specifications of IBW's pyrite concentrate in terms of quality and grade. Primary value drivers for pyrite concentrate are precious metals content and sulphur grade. Approximately 78% of gold and 47% of silver (contained within LOM ore feed) reports to the pyrite concentrate, which has a sulphur grade of >48%. The value of the pyrite concentrate contributes approximately 66% of the total NSR.
Mineral Reserves and Resources
An updated Mineral Resource Estimate ("MRE") prepared by SLR, effective July 17, 2026, reports a Mineral Resource of 26.1 Million Indicated Tonnes grading 2.27% zinc, 1.12% lead, 0.45% copper, 52.0 g/t silver, and 1.04 g/t gold, with 33.2% sulphur with an additional 9.9 Million Inferred Tonnes grading 2.13% zinc, 1.00% lead, 0.50% copper, 36.0 g/t silver, and 0.50 g/t gold with 22.7% sulphur. Table 2 shows the MRE with Net Smelter Return ("NSR") values for IBW and each of the deposits. The resource model includes attributes for economic commodity grades, penalty-element grades, classification, material type, and density.
Table 2. Mineral Resource Estimate for IBW as of July 17, 2026
| Deposit | Class | Tonnage
Mt | Average Grade | NSR
$/t | Contained Metal |
Zn
(%) | Pb
(%) | Cu
(%) | Ag
(g/t) | Au
(g/t) | S
(%) | Zn
(kt) | Pb
(kt) | Cu
(kt) | Ag
(koz) | Au
(koz) | S
(kt) |
| La Romanera | Indicated | 22.4 | 2.15 | 1.03 | 0.38 | 53 | 1.10 | 35.9 | 236 | 481 | 230 | 84 | 38,199 | 792 | 8,018 |
| Inferred | 6.6 | 2.02 | 0.84 | 0.49 | 33 | 0.57 | 29.6 | 192 | 133 | 55 | 32 | 7,090 | 120 | 1,952 |
| El Cura | Indicated | 2.1 | 1.20 | 0.57 | 0.96 | 30 | 0.98 | 25.8 | 223 | 25 | 12 | 20 | 2,010 | 65 | 535 |
| Inferred | 0.9 | 0.98 | 0.42 | 0.74 | 19 | 0.62 | 18.7 | 165 | 9 | 4 | 7 | 556 | 18 | 168 |
| La Infanta | Indicated | 1.7 | 5.25 | 3.00 | 0.73 | 63 | 0.25 | 6.7 | 228 | 87 | 50 | 12 | 3,316 | 13 | 111 |
| Inferred | 2.4 | 2.87 | 1.67 | 0.45 | 50 | 0.28 | 5.6 | 147 | 70 | 41 | 11 | 3,901 | 22 | 135 |
| IBW | Indicated | 26.1 | 2.27 | 1.12 | 0.45 | 52 | 1.04 | 33.2 | 235 | 593 | 292 | 116 | 43,525 | 871 | 8,663 |
| Inferred | 9.9 | 2.13 | 1.00 | 0.50 | 36 | 0.50 | 22.7 | 178 | 212 | 100 | 50 | 11,547 | 161 | 2,256 |
Notes:- CIM (2014) definitions were followed for Mineral Resources.
- The reporting approach is based on underground mining via long-hole open stoping, on-site selective flotation of copper, lead, zinc, and pyrite concentrates, and off-site third-party treatment and refining of the flotation concentrates.
- Mineral Resources are reported within underground reporting shapes generated using a mineable stope optimiser (MSO) above NSR cut-off values of US$69.30/t for La Romanera, US$79.20/t for El Cura, and US$85.30/t for La Infanta. Only primary sulphide mineralisation is included in the Mineral Resource.
- The NSR values for each block were calculated using the following formulas:
- La Romanera - Zn(%)*US$14.72 + Pb(%)*US$6.79 + Cu(%)*US$40.39 + Ag(g/t)*US$1.10 + Au(g/t)*US$6.77 + S(%)*US$3.28
- El Cura - Zn(%)*US$13.11 + Cu(%)*US$93.42 + Ag(g/t)*US$0.85 + Au(g/t)*US$7.15 + S(%)*US$3.33
- La Infanta - Zn(%)*US$17.54 + Pb(%)*US$12.56 + Cu(%)*US$25.73 + Ag(g/t)*US$1.22 + Au(g/t)*US$10.52
- Factors in the NSR formulas are based on consensus long-term metal price forecasts, metallurgical recoveries from available testwork, and market studies, used to estimate payable factors, transport, treatment and refining charges. Inputs to the block NSR calculation are specified in notes 6 through 8.
- Mineral Resources are estimated using long-term prices of US$3,415/t Zn, US$2,425/t Pb, US$13,775/t Cu, US$65/oz Ag, US$3,500/oz Au and US$265/t pyrite concentrate (>48% sulphur).
- The following net metallurgical recoveries have been assumed:
- La Romanera - 78.7% Zn, 52.2% Pb, 41.5% Cu, 93.4% Ag, 89.8% Au, and 86.6% S.
- El Cura - 67.9% Zn, 0% Pb, 79.4% Cu, 79.8% Ag, 87.4% Au, and 82.7% S.
- La Infanta - 78.0% Zn, 78.3% Pb, 42.4% Cu, 88.2% Ag, 50.9% Au, and 0% S.
- The following net payabilities after deductions and penalties have been assumed:
- La Romanera - 74.6% Zn, 83.4% Pb, 79.0% Cu, 56.9% Ag, 6.7% Au, and 95.1% S.
- El Cura - 78.4% Zn, 0% Pb, 93.3% Cu, 49.5% Ag, 7.3% Au, and 95.8% S.
- La Infanta - 83.1% Zn, 83.3% Pb, 52.7% Cu, 66.6% Ag, 18.4% Au, and 0% S.
- Mineral Resources are inclusive of Mineral Reserves. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
- Numbers may not add or multiply due to rounding.
|
Source: SLR
Underlying the MRE are calculated Mineral Reserves for the La Romanera, El Cura, and La Infanta deposits. These were calculated assuming underground long-hole open stoping (LHOS) mining methods, with cemented paste backfill or dry rockfill. Reporting is based on NSR cut-off values of US$69.30/t for La Romanera, US$79.20/t for El Cura, and US$85.30/t for La Infanta. These comprise a maiden Probable Mineral Reserve estimate of 23.4 million tonnes at 2.30% zinc, 1.13% lead, 0.45% copper, 53 g/t silver, 1.07 g/t gold and 33.85% sulphur, supporting the 21-year mine life. IBW's Mineral Reserves by deposit are shown in Table 3. Inferred Mineral Resources were not converted to Mineral Reserves and were treated as waste in the Mineral Reserve estimate.
The PFS mine plan and economic analysis exclude Inferred Mineral Resources. Inferred Mineral Resources are too speculative geologically to have economic considerations applied to them, and there is no certainty that any Inferred Mineral Resources will be upgraded to Mineral Reserves or included in any future mine plan. Emerita may evaluate additional drilling to assess whether portions of the Inferred Mineral Resources can be upgraded in future studies, but no production schedule, mine-life extension, capital-cost reclassification or NPV impact should be inferred from these Inferred Mineral Resources.
Table 3. Summary of Mineral Reserves for IBW, Effective July 17, 2026
| Deposit | Class | Tonnage
Mt | Average Grade | NSR
$/t | Contained Metal |
Zn
(%) | Pb
(%) | Cu
(%) | Ag
(g/t) | Au
(g/t) | S
(%) | Zn
(kt) | Pb
(kt) | Cu
(kt) | Ag
(koz) | Au
(koz) | S
(kt) |
La
Romanera | Proven | - | - | - | - | - | - | - | - | - | - | - | - | - | - |
| Probable | 20.4 | 2.19 | 1.05 | 0.38 | 54 | 1.13 | 36.2 | 189 | 447 | 214 | 77 | 35,702 | 738 | 7,377 |
| El Cura | Proven | - | - | - | - | - | - | - | - | - | - | - | - | - | - |
| Probable | 1.8 | 1.23 | 0.58 | 1.01 | 31 | 1.01 | 26.3 | 187 | 22 | 11 | 18 | 1,794 | 59 | 474 |
| La Infanta | Proven | - | - | - | - | - | - | - | - | - | - | - | - | - | - |
| Probable | 1.2 | 5.57 | 3.15 | 0.77 | 65 | 0.25 | 6.9 | 195 | 70 | 39 | 10 | 2,614 | 10 | 87 |
IBW
| Proven | - | - | - | - | - | - | - | - | - | - | - | - | - | - |
| Probable | 23.4 | 2.30 | 1.13 | 0.45 | 53 | 1.07 | 33.85 | 189 | 539 | 264 | 105 | 40,109 | 807 | 7,938 |
Notes:- CIM (2014) definitions were followed for Mineral Reserves.
- The reporting approach is based on underground mining using long-hole open stoping with a minimum mining width of 3.0 m, on-site selective flotation of copper, lead, zinc, and pyrite concentrates, and off-site third-party treatment and refining of the flotation concentrates.
- Mineral Reserves are reported based on underground stope shapes generated using Deswik Stope Optimiser (DSO) and on 3D mine development shapes, which are scheduled and supported by a positive cashflow analysis. Mineral Reserves are stated above NSR cut-off values of US$69.30/t for La Romanera, US$79.20/t for El Cura, and US$85.30/t for La Infanta.
- Mineral Reserves are estimated using long-term prices of US$2,975/t Zn, US$2,200/t Pb, US$12,120/t Cu, US$55/oz Ag, US$3,000/oz Au and US$215/t pyrite concentrate (>48% sulphur).
- The NSR values for each block were calculated using the following formulas, with the factors based on consensus long-term metal price forecasts, metallurgical recoveries from available testwork, and market studies used to estimate payable factors, transport, treatment and refining charges:
- La Romanera - Zn(%)*US$11.80 + Pb(%)*US$5.70 + Cu(%)*US$33.72 + Ag(g/t)*US$0.92 + Au(g/t)*US$5.68 + S(%)*US$2.43
- El Cura - Zn(%)*US$10.63 + Cu(%)*US$81.37 + Ag(g/t)*US$0.69 + Au(g/t)*US$6.10 + S(%)*US$2.47
- La Infanta - Zn(%)*US$14.61 + Pb(%)*US$10.93 + Cu(%)*US$18.66 + Ag(g/t)*US$0.98 + Au(g/t)*US$7.85
- Mineral Reserves account for the following dilution:
- La Romanera stopes - 11.2% planned dilution, 6.7% unplanned dilution
- El Cura stopes - 19.4% planned dilution, 16.0% unplanned dilution
- La Infanta stopes - 20.9% planned dilution, 26.7% unplanned dilution
- Ore development - 0% dilution
- Mining recoveries of 95% were applied in long-hole stopes, 80% in sill pillar stopes, and 100% in ore development.
- Numbers may not add or multiply due to rounding.
|
Source: SLR
The updated MRE represents a 37% increase in total Indicated tonnage and a 46% increase in total Inferred tonnage on a Project-wide basis compared to the 2025 MRE (see the Company's press release dated March 17, 2025). The updated MRE is based on 352 drill holes, totaling 123,241 meters of drilling. Since drilling at IBW began in 2021, Emerita has drilled 138,400 meters and invested approximately US$34 million in exploration and drilling in the IBW area.
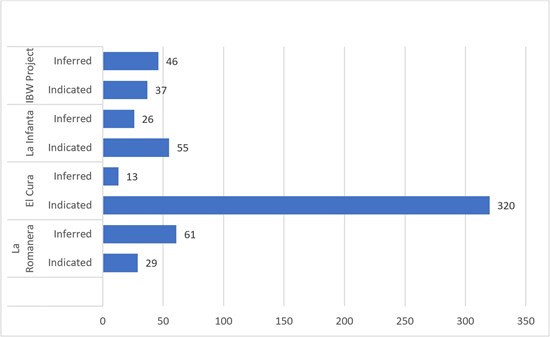
Source: Emerita Resources
Figure 2. Graph Indicating the Percentage Increase in Tonnage to the Mineral Resource Estimate for IBW when Compared to the 2025 Mineral Resource Estimate
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_emeritatwo.jpg
Initial and Sustaining Capital Estimates
Capital expenditures following a production decision are estimated at $566.7 million and consist of underground and surface infrastructure and facilities required prior to the start of operations. Approximately 33% of the total initial capital is associated with underground development and underground infrastructure, which includes the installation and deployment of the RailveyorTM material handling system and underground-to-surface discharge loop onto run-of-mine pad design. The RailveyorTM system has been used at other operations, including Agnico Eagle's Goldex Mine.
Initial capital costs also include over 23 kilometers of underground development, including an approximately 7-kilometer-long access decline to the La Romanera and El Cura deposits to safeguard a protected area. An additional 52% of the total initial capital is associated with the surface facilities and infrastructure, which include the construction of the processing plant, water management system, initial phase of the Tailings Storage Facility ("TSF"), capitalized operating cost and other supporting and ancillary surface infrastructure typically required at a mine site. The remaining 15% of the total initial capital is associated with owner costs, as well as indirect costs and project contingency.
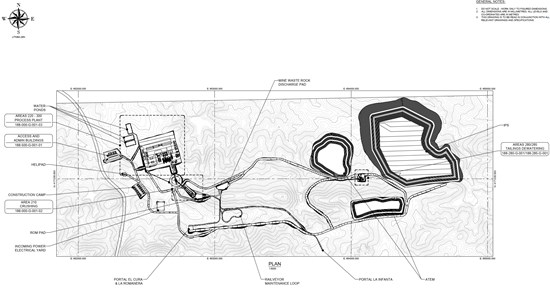
Source: SLR
Figure 3. Overall Site Layout of IBW Surface Facilities
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_5cfbd225742a7b3b_003full.jpg
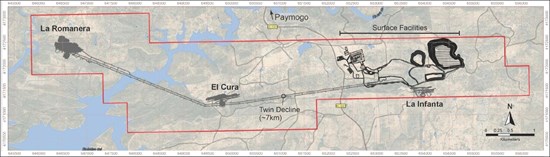
Source: SLR
Figure 4. Plan View of Underground Mine and Surface Development for IBW
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_5cfbd225742a7b3b_004full.jpg
The IBW surface layout is shown in Figure 3, and Figure 4 illustrates the mine and surface facilities layout in relation to the La Romanera, El Cura and La Infanta deposits.
Sustaining capital is estimated at $280 million. This total includes $250 million for continued mine development and $30 million for wastewater management, TSF development and paste/backfill costs. Post-mine closure costs are calculated at $12 million. Table 4 provides additional detail on a yearly production basis of initial, sustaining, and closure capital costs.
Table 4. Life-of-Mine Capital Costs for IBW
| Year | Initial Capital Costs
(US$ million) | Sustaining Capital
(US$ million) | Closure
(US$ million) | Total LOM Capex
(US$ million) |
| -5 | 61.9 | 0.0 | - | 61.9 |
| -4 | 33.9 | 0.0 | - | 33.9 |
| -3 | 90.5 | 0.0 | - | 90.5 |
| -2 | 184.0 | 0.1 | - | 184.1 |
| -1 | 172.8 | 0.1 | - | 172.9 |
| 1 | 23.6 | 27.7 | - | 51.3 |
| 2 | - | 20.8 | - | 20.8 |
| 3 | - | 20.9 | - | 20.9 |
| 4 | - | 23.1 | - | 23.1 |
| 5 | - | 29.2 | - | 29.2 |
| 6 | - | 19.5 | - | 19.5 |
| 7 | - | 13.9 | - | 13.9 |
| 8 | - | 8.2 | - | 8.2 |
| 9 | - | 14.6 | - | 14.6 |
| 10 | - | 25.8 | - | 25.8 |
| 11 | - | 8.7 | - | 8.7 |
| 12 | - | 6.9 | - | 6.9 |
| 13 | - | 8.9 | - | 8.9 |
| 14 | - | 12.9 | - | 12.9 |
| 15 | - | 18.5 | - | 18.5 |
| 16 | - | 6.6 | - | 6.6 |
| 17 | - | 7.0 | - | 7.0 |
| 18 | - | 2.4 | - | 2.4 |
| 19 | - | 1.2 | - | 1.2 |
| 20 | - | 1.2 | - | 1.2 |
| 21 | - | 0.9 | 1.2 | 2.1 |
| 22 | - | - | 3.0 | 3.0 |
| 23 | - | - | 6.0 | 6.0 |
| 24 | - | - | 1.8 | 1.8 |
| Total LOM | 566.7 | 279.5 | 12.0 | 858.2 |
Source: SLR. Note: Numbers may not add due to rounding.
Operating Cost Estimates
Total LOM on-site operating costs are estimated at US$2.03 billion, comprising mining, processing, G&A costs, water treatment, waste management, backfill operations, and progressive rehabilitation. Additional LOM off-site costs are estimated at US$0.89 billion, of which concentrate penalties account for approximately 57% of the total, followed by transportation and sales costs (32%) and treatment and refining charges (TC/RC) (10%). Future improvements in metallurgy may reduce these costs and represent potential optimization opportunities; however, no such improvements are reflected in the PFS.
Table 5. IBW Life-of-Mine Operating Costs
| Cost Category | Cost
(US$ million) | Cost
(US$/t Ore Processed) |
| Mining | 882 | 37.61 |
| Processing | 708 | 30.20 |
| General and Administrative | 70 | 2.97 |
| Water Treatment, Waste Management and Backfill | 363 |
|
| Contact Water Treatment |
| 3.52 |
| Capital Recovery Charge for Water Treatment Plant |
| 6.06 |
| Mine Waste / ATEM |
| 0.15 |
| Tailings / IPS |
| 0.53 |
| Paste Backfill |
| 5.24 |
| Progressive Rehabilitation | 5 | 0.22 |
| Total On-Site Operating Costs | 2,028 | 86.49 |
| Treatment and Refining Charges (TC/RC) | 92 | - |
| Concentrate Penalties | 506 | - |
| Transportation and Sales | 287 | - |
| Total Off-Site Costs | 886 | - |
| Total Operating Costs (On-site and Off-site) | 2,914 | - |
Source: SLR
Mining costs represent approximately 43% of total unit operating costs and include underground development, production drilling, blasting, loading, hauling, ground support, ventilation, pumping, labour, maintenance, and power consumption. Processing activities represent the second most intensive operating cost at 35% of the total unit costs. Unit operating costs are shown in Table 6.
Table 6. Unit Operating Costs for IBW Years 1-21
| Cost Category | Cost
(US$/t Ore Processed) |
| Mining Operating Costs | 37.61 |
| Processing Costs | 30.20 |
| Contact Water Treatment | 3.52 |
| Capital Recovery Charge for Water Treatment Plant | 6.06 |
| Mine Waste / ATEM | 0.15 |
| Tailings / IPS | 0.53 |
| Paste Backfill | 5.24 |
| G&A | 2.97 |
| Progressive Rehabilitation | 0.22 |
| Total Operating Costs | 86.49 |
Source: SLR
Processing Design and Production
All three orebodies will be treated using the same process plant. La Romanera will be the main ore source, with ore from El Cura and La Infanta blended with it to even out the head grades and process requirements. The process design criteria are based on La Romanera average head grades and test work, as La Romanera ore constitutes approximately 85% of the total tonnage for the three orebodies.
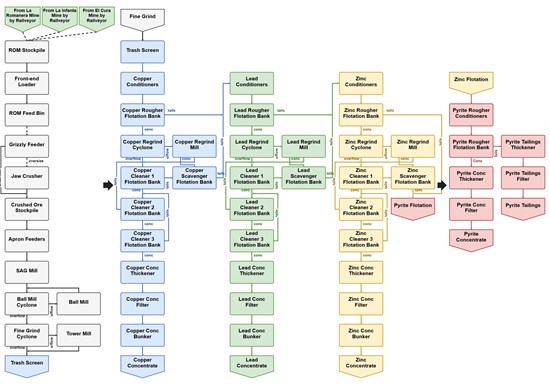
There will be four flotation concentrates produced: copper, lead, zinc, and precious metals-bearing pyrite.
Source: SLR
Figure 5. Process Flowsheet Diagram for IBW
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_5cfbd225742a7b3b_005full.jpg
The processing flowsheet is considered conventional, with the process plant design based on a flowsheet comprising a single-stage crushing circuit followed by semi-autogenous grinding ("SAG") milling with pebble crushing in closed circuit, ball milling with classification cyclones in closed circuit, tower milling fine grinding with classification cyclones in closed circuit, four flotation circuits in the sequence of copper -> lead -> zinc -> pyrite, concentrate thickening and tails thickening. The final tailings are dewatered to a filter cake for paste backfill requirements and dry stacking.
The key design features or criteria for the plant were:
- Nominal throughput of 1.2 Mtpa
- A primary crusher and coarse ore stockpile with a 75% availability
- Milling and flotation circuits with all downstream processing units with an availability of 92%
Table 7 provides a LOM production summary for IBW.
Table 7. Production Summary for IBW
| Year | Total Ore Mined
(kt) | Total Ore Feed to Flotation
(kt) | Grades Processed | Contained Metal Processed |
| Zn (%) | Pb (%) | Cu (%) | Ag (g/t) | Au (g/t) | S (%) | Zn (kt) | Pb (kt) | Cu (kt) | Ag (kg) | Au (kg) | S (kt) |
| -1 | 155 | - | 1.22 | 0.88 | 0.71 | 55.45 | 1.07 | 31.91 | 1.9 | 1.4 | 1.1 | 8,617 | 166 | 50 |
| 1 | 641 | 797 | 1.97 | 1.26 | 0.56 | 63.10 | 1.27 | 34.66 | 12.7 | 8.1 | 3.6 | 40,479 | 812 | 222 |
| 2 | 1,200 | 1,200 | 2.83 | 1.39 | 0.50 | 65.06 | 1.19 | 35.05 | 34.0 | 16.7 | 6.0 | 78,073 | 1,432 | 421 |
| 3 | 1,200 | 1,200 | 2.99 | 1.22 | 0.46 | 59.95 | 1.22 | 37.10 | 35.9 | 14.6 | 5.5 | 71,938 | 1,467 | 445 |
| 4 | 1,200 | 1,200 | 3.34 | 1.34 | 0.53 | 59.89 | 1.46 | 37.26 | 40.1 | 16.1 | 6.4 | 71,862 | 1,751 | 447 |
| 5 | 1,200 | 1,200 | 2.33 | 1.12 | 0.45 | 53.11 | 1.48 | 36.72 | 27.9 | 13.5 | 5.3 | 63,726 | 1,779 | 441 |
| 6 | 1,200 | 1,200 | 2.68 | 1.22 | 0.33 | 54.34 | 1.83 | 38.28 | 32.2 | 14.6 | 4.0 | 65,202 | 2,192 | 459 |
| 7 | 1,200 | 1,200 | 2.90 | 1.27 | 0.33 | 58.39 | 1.51 | 35.88 | 34.8 | 15.2 | 4.0 | 70,058 | 1,812 | 431 |
| 8 | 1,200 | 1,200 | 2.39 | 1.07 | 0.39 | 69.80 | 1.17 | 33.88 | 28.7 | 12.9 | 4.7 | 83,751 | 1,402 | 407 |
| 9 | 1,200 | 1,200 | 1.90 | 0.97 | 0.40 | 61.75 | 0.98 | 33.84 | 22.7 | 11.7 | 4.8 | 74,091 | 1,172 | 406 |
| 10 | 1,200 | 1,200 | 1.82 | 0.90 | 0.42 | 53.44 | 0.94 | 33.94 | 21.8 | 10.8 | 5.0 | 64,122 | 1,124 | 407 |
| 11 | 1,200 | 1,200 | 1.71 | 0.86 | 0.40 | 49.06 | 0.85 | 31.80 | 20.5 | 10.3 | 4.8 | 58,861 | 1,020 | 382 |
| 12 | 1,200 | 1,200 | 1.96 | 1.09 | 0.41 | 58.46 | 1.04 | 32.12 | 23.5 | 13.1 | 4.9 | 70,147 | 1,249 | 385 |
| 13 | 1,200 | 1,200 | 1.70 | 0.97 | 0.40 | 45.29 | 0.79 | 31.16 | 20.4 | 11.6 | 4.8 | 54,345 | 945 | 374 |
| 14 | 1,200 | 1,200 | 1.53 | 0.89 | 0.45 | 42.23 | 0.71 | 30.24 | 18.4 | 10.7 | 5.4 | 50,678 | 854 | 363 |
| 15 | 1,200 | 1,200 | 1.77 | 1.01 | 0.53 | 43.82 | 0.76 | 30.20 | 21.2 | 12.1 | 6.4 | 52,573 | 912 | 362 |
| 16 | 1,200 | 1,200 | 2.55 | 1.25 | 0.46 | 44.75 | 0.68 | 30.98 | 30.6 | 15.1 | 5.6 | 53,699 | 818 | 372 |
| 17 | 1,200 | 1,200 | 2.86 | 1.35 | 0.47 | 49.85 | 0.74 | 32.97 | 34.3 | 16.2 | 5.6 | 59,826 | 889 | 396 |
| 18 | 1,200 | 1,200 | 2.60 | 1.28 | 0.51 | 43.93 | 0.87 | 34.45 | 31.2 | 15.3 | 6.1 | 52,721 | 1,045 | 413 |
| 19 | 1,200 | 1,200 | 1.70 | 0.88 | 0.42 | 40.92 | 1.02 | 34.29 | 20.4 | 10.5 | 5.0 | 49,100 | 1,221 | 412 |
| 20 | 837 | 837 | 2.33 | 1.19 | 0.49 | 52.96 | 1.09 | 35.01 | 19.5 | 9.9 | 4.1 | 44,350 | 909 | 293 |
| 21 | 215 | 215 | 2.78 | 1.61 | 0.89 | 43.41 | 0.56 | 23.65 | 6.0 | 3.5 | 1.9 | 9,333 | 120 | 51 |
| Total LOM | 23,448 | 23,448 | 2.30 | 1.13 | 0.45 | 53 | 1.07 | 33.85 | 538.7 | 263.9 | 104.9 | 1,247,552 | 25,092 | 7,938 |
Source: SLR
Product Marketing
IBW is expected to produce four streams of revenue through the sale of copper, zinc, lead, and precious metals-bearing pyrite concentrates. The zinc concentrate from IBW is projected to contain approximately 50% zinc, together with payable gold and silver credits. Projected lead concentrate from IBW contains approximately 27% lead, along with silver and gold credits. The study notes that precious metal credits enhance the attractiveness of the lead concentrate and help offset penalties associated with observed mercury content. Projected copper concentrate from IBW contains approximately 20% copper, together with gold and silver credits.
Pyrite concentrate is primarily marketed as a source of sulphur and is predominantly used in the manufacturing of sulphuric acid. Sulphuric acid is one of the world's highest volume industrial chemicals and is a critical reagent in fertiliser production, metal processing, chemical manufacturing, and battery material supply chains. Consequently, demand for pyrite concentrate is closely linked to global sulphuric acid consumption. Unlike conventional base metal concentrates, the pyrite concentrate value is derived from sulphur content as well as gold and silver precious metals content.
The IBW pyrite concentrate contains notable concentrations of both gold and silver in addition to a high sulphur content (>48% sulphur) that make this material attractive from a marketing perspective. No commercial terms have been negotiated for IBW; however, the Company commissioned Claight Market Research, a market research and consulting firm with experience in the minerals sector, which provided Emerita with a customized analysis of IBW's pyrite concentrate metallurgical specifications. This research provided long-term price forecasting that SLR adopted for the IBW pyrite concentrate. A Base Case assumption of US$274/t was adopted for the IBW pyrite concentrate. The Claight research report also provided industry feedback, including reviews by global commodity trading firms, on how precious metals-bearing concentrate pricing is reconciled, which includes refinery charges, sulphur content, deductions, penalties and how precious metals payable rates are applied. These formulae were adopted in the cashflow analysis for the PFS and are considered indicative for the purposes of this PFS.
Zinc concentrates are noted to be of normal-to-high-quality commercial zinc grade, with recoverable precious metals enhancing its attractiveness to smelters. Lead concentrate is considered commercially attractive due to its precious metal content, and market studies concluded that the concentrate should be acceptable to the market under normal commercial arrangements. For copper concentrates it was concluded that the concentrate's profitability and market attractiveness are largely driven by its precious metal content, and that the concentrate should be commercially saleable, subject to appropriate offtake agreements. Penalty elements such as mercury and antimony have been noted as present in several of the base metal concentrates with appropriate deductions incorporated into the pricing.
Table 8 indicates the Base Case metal prices adopted in the PFS. Table 9 provides indicative assumptions for payabilities, treatment and refining charges and transportation costs as reported in the PFS.
Table 8. Long-Term (Base Case) Metal Price Assumptions and September 2026 Pricing
| Long-Term Metal Prices | Units | Consensus
(Base Case) | September 2026
Average Spot |
| Pyrite Concentrate | US$/t concentrate | 274 | 274* |
| Copper Price | US$/t | 11,470 | 14,483 |
| Lead Price | US$/t | 2,050 | 1,871 |
| Zinc Price | US$/t | 2,980 | 4,020 |
| Gold Price | US$/oz | 3,750 | 4,322 |
| Silver Price | US$/oz | 52 | 65 |
*Pyrite concentrate specific to IBW's specification. Pyrite concentrate is not traded on a metal exchange. Real-term price based on Claight Market Research report long-term average.
Source: SLR
Table 9. Base Case Commercial Assumptions Adopted in IBW PFS
| Commercial Assumption | Zinc Concentrate | Lead Concentrate | Copper Concentrate | Pyrite Concentrate |
Long-Term Price
Assumption | Zinc Price US$2,980/t | Lead Price US$2,050/t | Copper Price US$11,470/t | Pyrite Concentrate Price US$274/t, exclusive of precious metal credits (Claight, 2026 market study); gold and silver credits payable separately as below |
| Payable Metal, Deduction, and Payability: Zn / Pb / Cu | 85.00% of contained Zn after an 8-unit deduction, subject to the minimum concentrate-grade threshold | Lesser of (Pb less 3 units) or 95.00% of contained Pb | Lesser of (Cu less 1 unit) or 96.50% of contained Cu | Not applicable; priced per tonne of concentrate |
| Payable Metal, Deduction, and Payability: Ag | 70.00% of remaining Ag after a 93.3 g/t deduction, subject to minimum grade and deduction thresholds | 95.00% of remaining Ag after a 50 g/t deduction | 90.00% of contained Ag, no deduction | Deduct 25 g/t Ag and pay 90.00% of the remainder |
| Payable Metal, Deduction, and Payability: Au | 70.00% of remaining Au after a 1 g/t deduction | 95.00% of remaining Au after a 1 g/t deduction | 90.00% of contained Au, no deduction, subject to the applicable grade threshold | Deduct 1 g/t Au and pay 90.00% of the remainder |
Treatment Charge
(US$/dmt) | 85.0 | 5.0 | 40.0 | Nil |
| Refining Charge | Nil | Au US$15.00/oz; Ag US$0.50/oz | Cu US$0.02/lb; Au and Ag nil | Au US$5.0/oz; Ag US$0.40/oz |
| Concentrate Transportation and Handling | Road to the Port of Huelva, approximately 80 km: transport €7.89/t of concentrate and port handling €7.97/t of concentrate. Using an assumed foreign exchange rate of 1.10 US$/€, these costs equate to US$8.68/t and US$8.77/t, respectively, for a total concentrate transportation and handling cost of approximately US$17.45/t. |
| Total Payable for Concentrates, LOM (US$ million) | 1,145 | 739 | 852 | 4,737 |
| Total NSR, LOM (US$ million) | 895 | 670 | 654 | 4,368 |
Source: SLR
Economic Analysis
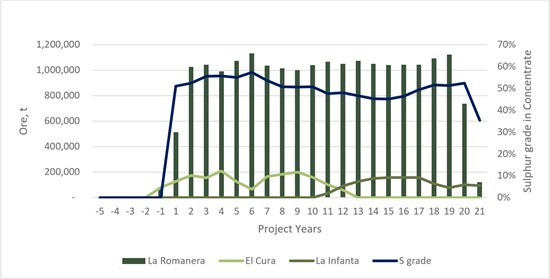
The economic analysis of IBW was developed using an annual, unlevered cash flow model based on the mine production schedule, process design criteria, capital and operating cost estimates, and commercial assumptions developed for the PFS. The financial model is based on the LOM production schedule comprising ore feed from the La Romanera, El Cura, and La Infanta deposits. La Romanera is the principal source of plant feed, with production from El Cura and La Infanta supplementing the feed over the LOM. Stockpiled ore is reclaimed where required to balance mine production and maintain the scheduled plant throughput. The production schedule is shown in Figure 6.
Source: Emerita Resources
Figure 6. IBW Life-of-Mine Ore Feed Production by Deposit and Sulphur Grade
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_emeritasix.jpg
The financial model forecasts production of four saleable concentrates: copper, lead, zinc, and pyrite concentrates. The Base Case metal price assumptions for copper, zinc, lead, gold, and silver are based on consensus forecast pricing published by leading financial institutions providing regular commodity price forecasts. Pyrite concentrate pricing is based on the project-specific market study produced by Claight Market Research. IBW is expected to produce a precious metals-bearing pyrite concentrate containing more than 48% sulphur, which is considered a high-grade product in the target market. Base Case pricing is shown in Table 8.
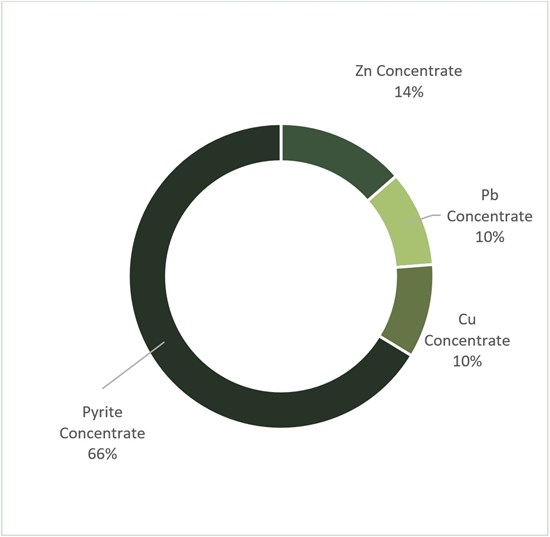
IBW benefits from multiple revenue streams from the production of zinc, lead, copper, and pyrite concentrates, including payable gold and silver contained within the base-metal concentrates. On a LOM basis, pyrite concentrate represents 66% of IBW NSR, with zinc, lead, and copper concentrates contributing approximately 14%, 10%, and 10%, respectively, as illustrated in Figure 7.
Source: SLR
Figure 7. IBW NSR Contribution by Concentrate Type and Schematic Pricing Buildup
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_emeritaseven.jpg
At the Base Case commodity price assumptions, IBW generates an after-tax NPV of approximately US$776 million at an 8% real discount rate and an after-tax internal rate of return ("IRR") of 23.51%. The corresponding payback period is equivalent to approximately 1 year and 11 months following the commencement of production, and approximately 6 years and 11 months from the commencement of IBW development. Initial capital expenditure is estimated at approximately US$567 million. At an 8% discount rate, IBW has a Profitability Index (PI) of 2.37.
Economic Base Case results are provided in Table 1.
Sensitivity Analysis
Cash flow sensitivities were run on the following key drivers on IBW: commodity prices, on-site and off-site operating costs, and initial capital costs. IBW sensitivities were evaluated by varying selected parameters from -10% to +10%, while holding all other technical and economic assumptions constant. The sensitivity effects for NPV and IRR are shown in Table 10 and Table 11, respectively.
Table 10. After-Tax Sensitivity Analysis Effect on NPV for IBW (US$ million)
| Sensitivity Analysis - NPV @ 8% |
| Change in Parameter | -10% | 0% | +10% |
| On-site operating costs | 829 | 776 | 724 |
| Off-site operating costs | 799 | 776 | 753 |
| Initial Capital Cost | 813 | 776 | 740 |
| Pyrite Concentrate Price | 681 | 776 | 872 |
| Copper Price | 763 | 776 | 790 |
| Lead Price | 770 | 776 | 783 |
| Zinc Price | 748 | 776 | 805 |
| Gold Price | 750 | 776 | 803 |
| Silver Price | 747 | 776 | 806 |
Source: SLR
Table 11. After-Tax Sensitivity Analysis Effect on IRR of IBW
| Sensitivity Analysis - IBW IRR |
| Change in Parameter | -10% | 0% | +10% |
| On-site operating costs | 24.3% | 23.5% | 22.7% |
| Off-site operating costs | 23.8% | 23.5% | 23.2% |
| Initial Capital Cost | 25.4% | 23.5% | 21.9% |
| Pyrite Concentrate Price | 22.1% | 23.5% | 24.9% |
| Copper Price | 23.3% | 23.5% | 23.7% |
| Lead Price | 23.4% | 23.5% | 23.6% |
| Zinc Price | 23.1% | 23.5% | 23.9% |
| Gold Price | 23.0% | 23.5% | 24.0% |
| Silver Price | 23.0% | 23.5% | 24.0% |
Source: SLR
Considerations and Opportunities
The current Pre-Feasibility Study identifies key opportunities that would enhance and de-risk IBW:
- The PFS mine plan and economic analysis exclude Inferred Mineral Resources. Inferred Mineral Resources are too speculative geologically to have economic considerations applied to them, and there is no certainty that any Inferred Mineral Resources will be upgraded to Mineral Reserves or included in any future mine plan. Emerita may evaluate additional drilling to assess whether portions of the Inferred Mineral Resources can be upgraded in future studies, but no production schedule, mine-life extension, capital-cost reclassification or NPV impact should be inferred from these Inferred Mineral Resources.
- As reported in Emerita's public disclosure, all of the deposits at IBW remain open to expansion. Emerita reported drilling results at its El Cura deposit until the Company's announced cessation of drilling on June 2, 2026 (see press release dated July 9, 2026, for last reported results). All of the IBW deposits start at or near surface and remain open at depth. There is no certainty that additional drilling will result in additional Mineral Resources.
- A better geotechnical and hydrogeological understanding of IBW can provide more confidence in the lateral development rates for the twin decline designed in the PFS. The PFS adopts conservative development rates due to the lack of informative data in these disciplines. The acquisition of this data, already in progress, will help inform whether the IBW's development rates would align with other benchmarks measured at other projects in the Iberian Pyrite Belt, which are as much as 20% greater than those considered in the PFS and which could lead to a shorter preproduction timeline.
- High-pressure-grinding-roll-based comminution may lower power consumption and emissions and reduce operating costs for IBW; however, this has not been assessed in the PFS and further study is required.
- Emerita has initiated the environmental permitting process for IBW, including the application for the Unified Environmental Authorization (AAU, its Spanish acronym). The timing and outcome of permitting remain subject to regulatory review, environmental assessment, public consultation, satisfaction of conditions, financing, engineering and other risks, and there can be no assurance that permits will be obtained on the expected timeline or at all.
IBW has been granted strategic project status by the Regional Government of Andalusia. As such, IBW benefits from the valuable support of the Government's Project Acceleration Unit (UAP), which helps coordinate and streamline the permitting process for investment projects considered important to the economic and social development of the region.
In parallel, Emerita has established the "Fundación Emerita Compromiso Sostenible" to support the social, economic and sustainable development of local communities, particularly in the Andévalo region of Huelva, where IBW is located. Through the Foundation, the company aims to strengthen its ties with local communities and contribute to their long-term well-being and prosperity.
At the effective date of this press release, no concentrate offtake agreements, agency agreements, hedging arrangements or forward sales contracts have been executed for the IBW project. The treatment charges, refining charges, payabilities, penalties and concentrate transportation costs adopted in the PFS are based on benchmark market terms and independent market studies commissioned by the Company. Definitive concentrate sale agreements are expected to occur under industry-standard concentrate purchase agreements negotiated at the time of production.
Technical Report
Further information about the PFS and the Mineral Reserve Statement referenced in this news release will be provided in a technical report prepared in accordance with NI 43-101, which will be filed on SEDAR+ under the Company's profile at www.sedarplus.ca within 45 days of this news release. Known risks that could materially affect the potential development of the Mineral Resources and Mineral Reserves include permitting and environmental approval risks, metallurgical and concentrate-marketing risks, pyrite concentrate pricing and offtake risks, concentrate penalties, geotechnical and hydrogeological risks, capital and operating cost escalation, commodity-price and exchange-rate variability, infrastructure and water-management requirements, and community and regulatory approvals.
Qualified Persons
The Pre-Feasibility Study was prepared by SLR Consulting ("SLR") in accordance with NI 43-101 and the CIM Definition Standards, under the supervision of Frank Browning, MSc, FGS, CGeol , James W.G. Turner, MCSM, MIMMM, CEng, Christopher Penna, CEng, Liam Johnson, RPEQ, MAusIMM CP (Geotech), Christopher Paul Stinton, CEng IMMM , Arturo Gutierrez del Olmo, PhD. (Mining), Eur Ing, MIMMM , Alison Brianna Allen, BSc, MSc, CEnv, FIMMM, MISEP, Veronika Luneva, MAussIMM, MSc, IMC (CFA UK Level 4) each of whom is a Qualified Person independent of Emerita for the purposes of NI 43-101.
Scientific and technical information in this news release has been reviewed and approved by Danniel Oosterman, PGeo, who is a "Qualified Person" as defined by National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101") and Project Director of Emerita Resources Corp., and is therefore not independent of Emerita. Mr. Oosterman has verified the data disclosed in this news release, including the sampling, analytical and test data underlying the information. The verification procedures included procedures creating the drill-hole database, sampling and QA/QC data, review of those data prior to delivery to the independent consultant, and review of the relevant sections of the PFS. There were no material limitations on the verification process.
About Emerita Resources Corp.
Emerita is a natural resource company engaged in the acquisition, exploration and development of mineral properties in Europe, with a primary focus on exploring in Spain. The Company's corporate office and technical team are based in Sevilla, Spain, with an administrative office in Toronto, Canada.
NEITHER TSX VENTURE EXCHANGE NOR ITS REGULATION SERVICES PROVIDER (AS THAT TERM IS DEFINED IN THE POLICIES OF THE TSX VENTURE EXCHANGE) ACCEPTS RESPONSIBILITY FOR THE ADEQUACY OR ACCURACY OF THIS RELEASE.
Cautionary Note Regarding Forward-looking Information
This press release contains "forward-looking information" within the meaning of applicable Canadian securities legislation. Forward-looking information includes statements and information regarding the PFS, projected NPV, IRR, payback, mine life, production rates, throughput, recoveries, capital and operating costs, commodity and concentrate price assumptions, permitting timelines, development timelines, optimization opportunities, potential future resource conversion, potential concentrate marketing, and Emerita's plans for the IBW project. Such information is based on material assumptions, including the metal, sulphur and concentrate prices and exchange rates used in the PFS, the accuracy of the Mineral Resource and Mineral Reserve estimates, metallurgical recoveries, capital and operating cost estimates, the discount rate applied, the receipt of permits on the expected timeline and the availability of financing. Generally, forward-looking information can be identified by the use of forward-looking terminology such as "plans", "expects" or "does not expect", "is expected", "budget", "scheduled", "estimates", "forecasts", "intends", "anticipates" or "does not anticipate", or "believes", or variations of such words and phrases or state that certain actions, events or results "may", "could", "would", "might" or "will be taken", "occur" or "be achieved". Forward-looking information is subject to known and unknown risks, uncertainties and other factors that may cause the actual results, level of activity, performance or achievements of Emerita, as the case may be, to be materially different from those expressed or implied by such forward-looking information, including but not limited to: general business, economic, competitive, geopolitical and social uncertainties; commodity price and exchange rate volatility; permitting and environmental approval risks; metallurgical, concentrate marketing, offtake and penalty risks; capital and operating cost escalation; financing, construction and execution risks; the actual results of current exploration activities; risks associated with operation in foreign jurisdictions; foreign operations risks; and other risks inherent in the mining industry. Although Emerita has attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking information, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such information will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking information. Emerita does not undertake to update any forward-looking information, except in accordance with applicable securities laws.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/321646

© 2026 Canjex Publishing Ltd. All rights reserved.